Russia proposes IT tax treatment for digital book subscriptions
Russia proposes extending IT tax treatment to digital book subscriptions; adoption and consumer effects remain unconfirmed.
Russia’s government has proposed extending the tax treatment available to IT organisations to subscription services providing ebooks and audiobooks. The amendments were submitted to the State Duma as part of the budget package, Interfax reported on 2 October. The report concerns a bill; it does not establish that the extension has already been adopted or applies to every digital book service.
The proposal concerns the format of digital content
The explanatory note describes an aim to create equal tax conditions for different forms of digital content. Subscription book services would be considered alongside audiovisual services and music platforms. The principal development is therefore a proposed widening of the organisations eligible for the treatment, rather than a new method of buying an individual book.
The amendments concern Tax Code provisions defining conditions for IT-company preferences. The proposed addition includes access to electronic books, other electronic publications and graphic images. The report also describes audiobooks offered through a subscription model. The precise set of qualifying organisations would depend on adopted provisions and their requirements, rather than solely on a news description of the content they provide.
A stated purpose is different from a measured effect
The budget-package documents connect the continued IT regime with the attractiveness of the Russian jurisdiction, investment in domestic solutions and digital development across the economy. Those are stated policy aims. They are not evidence that book-service investment has already increased, subscription prices have changed or a defined number of new users has joined. The source provides no measured results of that kind.
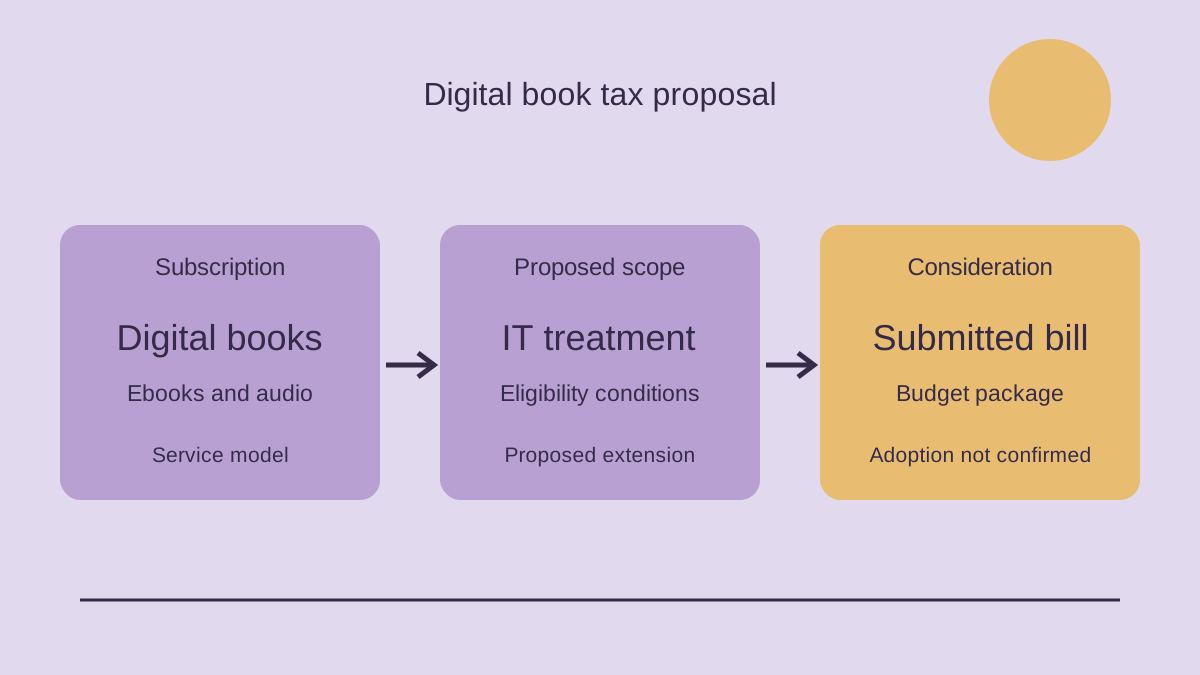
- The proposed scope is subscription access to digital books.
- The explanatory comparison is with other digital content formats.
- The reported status is amendments submitted with the budget package.
- The report does not confirm adoption of the extension.
Parliamentary consideration remains the next stage
The subsequent status of the proposal and its final conditions matter to businesses and readers. A subscription business model alone does not establish that a particular organisation is entitled to a tax regime; the applicable requirements must be assessed separately against the rules in force. This report describes the proposal rather than calculating tax for an individual service or recommending accounting changes before an adopted decision exists.
The distinction between a submitted bill and an operative rule also matters when discussing consumer consequences. A tax change, even if adopted, does not automatically determine a subscription price. The accurate current description is proposed conditions for digital book services in Russia, without claiming that lower prices or a larger catalogue have already resulted.
Leave a comment
Your comment is awaiting moderation.